 Zakirin
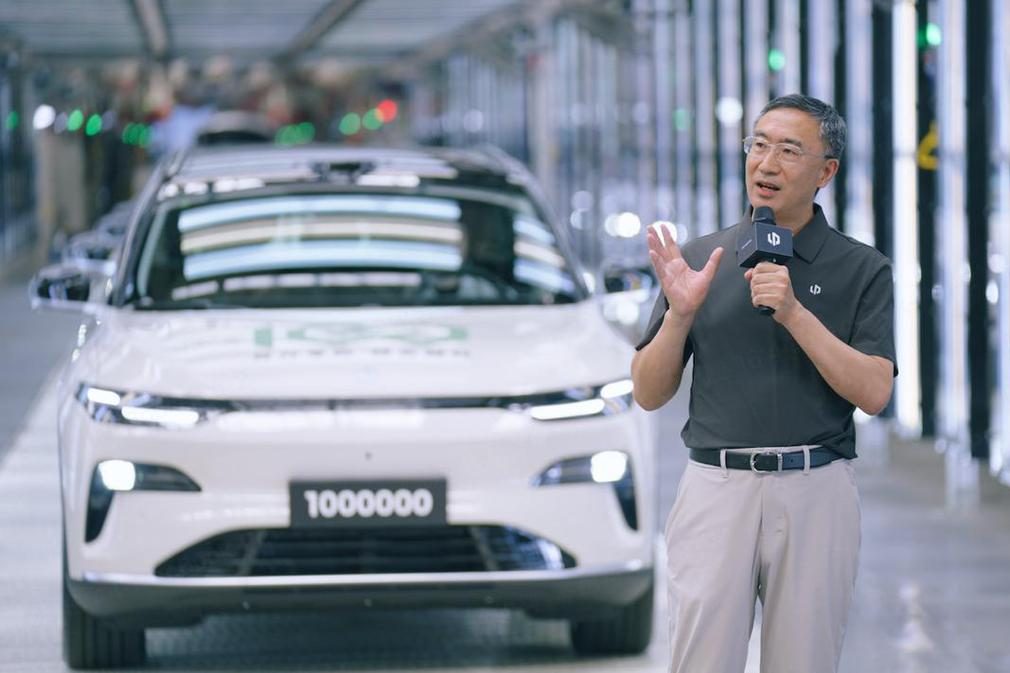
A senior executive at Leapmotor has warned that the majority of Chinese automotive brands currently expanding into international export markets will fail to survive over the long term, predicting widespread market consolidation as new entrants struggle with aftersales support, parts supply chains, and collapsing residual values.
- Leapmotor International commercial executive Danilo Annese projects that only a limited number of Chinese automakers entering global markets will achieve sustainable long-term operations.
- Market fallout is expected to be triggered by weak dealer networks, chronic replacement parts shortages, and erratic pricing strategies that erode vehicle resale values.
- Leapmotor relies on its global joint venture with Stellantis to mitigate these operational risks by integrating into established international distribution, warehousing, and service infrastructure.
The influx of dozens of Chinese new-energy vehicle (NEV) manufacturers into Europe, Southeast Asia, and Australasia has created intense market saturation. While aggressive pricing and high levels of standard equipment have driven early consumer interest, maintaining viable operations outside of China requires capital-intensive commitments that many independent startups cannot sustain.
| Strategic Parameter | Industry Risk Factors for New Entrants | Leapmotor Strategic Countermeasures |
| Market Survival Outlook | High attrition; only a minority of emerging Chinese marques projected to remain viable | Consolidation under multinational corporate backing |
| Retail & Dealer Footprint | Fragmented direct-to-consumer pop-ups or weak, non-exclusive independent networks | Integration into established multi-brand franchised dealer networks |
| Parts & Logistics Infrastructure | Long shipping lead times, customs delays, and lack of regional parts distribution hubs | Utilization of Stellantis regional parts warehouses and logistics corridors |
| Residual Value Protection | Volatile discounting and erratic product cycles leading to steep second-hand depreciation | Disciplined model lifecycles and structured trade-in valuations |
| Corporate Governance | Standalone Chinese domestic entities with limited cross-border balance sheet support | Leapmotor International (51% Stellantis, 49% Leapmotor joint venture) |
According to Danilo Annese, Vice President of Commercial Operations Europe at Leapmotor International, the deciding factor in whether an automotive brand earns lasting consumer trust is not initial retail pricing or interior technology, but the structural maturity of its aftersales ecosystem. Brands that enter export markets without dedicated regional parts warehousing face lengthy turnaround times for collision and warranty repairs, creating consumer backlash and operational bottlenecks.
A compounding challenge is the lack of disciplined product lifecycles. In the domestic Chinese market, rapid vehicle facelifts and aggressive discounting are common competitive tactics. However, applying rapid price reductions and uncoordinated model revisions in export markets severely damages vehicle resale values, alienates early adopters, and undermines vehicle financing and leasing programmes that rely on predictable depreciation curves.
To shield its operations from these systemic pitfalls, Leapmotor structured its global expansion through Leapmotor International, a joint venture established with multinational automotive group Stellantis, which holds a 51% controlling interest alongside a 20% equity stake in Leapmotor itself. This arrangement provides the brand with immediate access to Stellantis’ global footprint, allowing vehicles to be sold, serviced, and supplied with components through established commercial dealerships and centralized regional logistics hubs rather than building independent sales channels from scratch.
As global regulatory frameworks tighten and initial novelty demand subsides, international automotive markets are projected to enter a rationalisation phase, leaving well-capitalised manufacturers with resilient aftersales logistics to absorb the market share of exiting contenders.